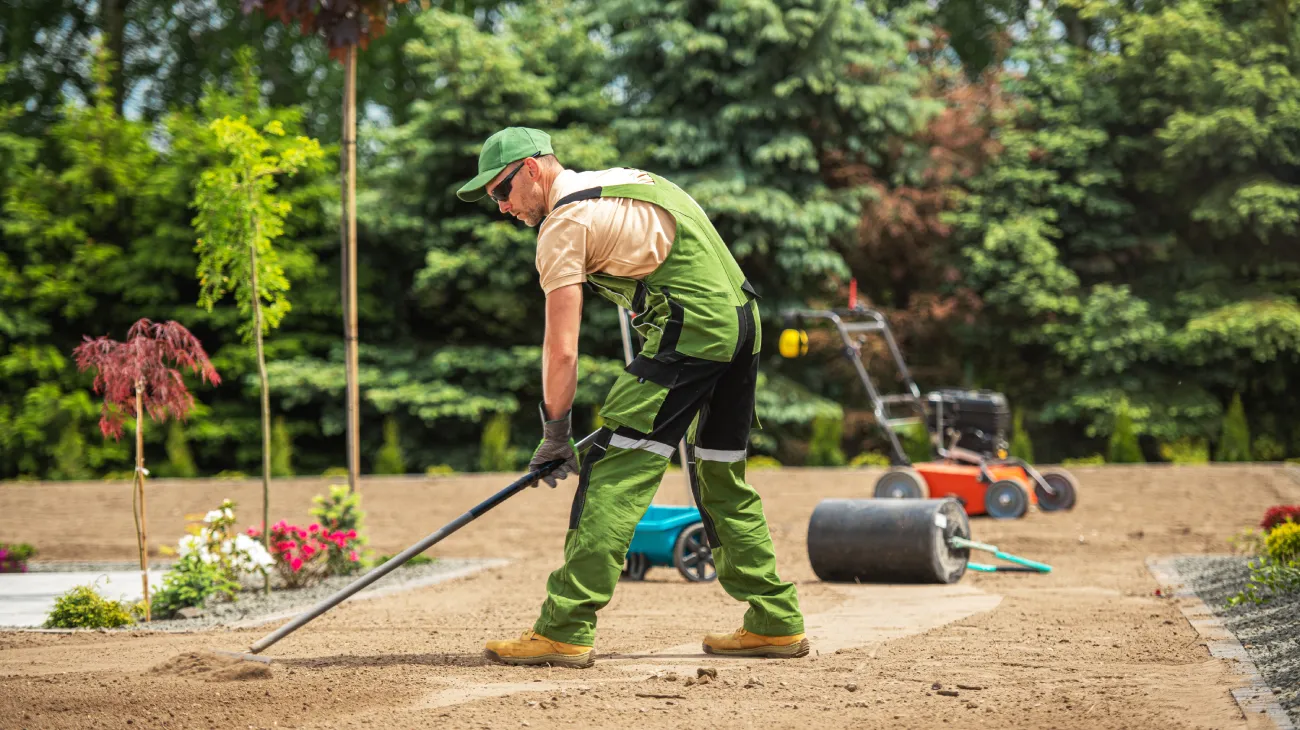

A landscaping project does not become valuable only when it is completed. Long before practical completion or final handover, significant time, labour and materials have already been invested into the project. Excavation has been completed, retaining walls constructed, irrigation systems installed and paving laid, yet the project may still be weeks away from completion.
During this period, landscaping contractors remain exposed to a range of risks. Severe weather, theft, vandalism, accidental damage and unexpected incidents involving other trades can all affect works that have already been completed but have not yet been handed over to the client.
This is where contract works insurance may become an important part of a landscaping business’s broader insurance programme. Rather than focusing on third-party liability, contract works insurance is generally designed to help protect the project itself while construction is still underway, subject to the policy terms, conditions and exclusions.
Understanding how this type of insurance operates can help landscaping contractors better manage project risk from commencement through to completion.
Why the period before handover carries significant risk
Many contractors assume the greatest risks arise once work has been completed. In reality, the construction phase often presents the greatest uncertainty because projects remain exposed while responsibility still sits with the contractor.
A landscaping project may progress over several weeks or months. During that time, expensive materials may be stored on site, completed sections of work remain vulnerable to accidental damage and multiple contractors may be working in close proximity.
For example, a retaining wall may already be finished while paving works continue nearby. Irrigation infrastructure may be installed beneath the ground before turf or planting is completed. Outdoor lighting, drainage systems and timber structures may all be in place before practical completion has been reached.
If damage occurs during this period, replacing completed work can involve both material costs and the labour required to rebuild sections of the project.
Understanding where responsibility lies before handover is an important consideration when reviewing your insurance programme.
What is contract works insurance?
Contract works insurance is generally intended to protect certain physical works forming part of a construction or landscaping project while those works are still in progress.
Depending on the policy wording, contract works insurance may respond to insured loss or damage affecting:
- Works in progress.
- Materials awaiting installation.
- Newly installed landscaping components.
- Temporary works associated with the project.
- Certain site materials and equipment.
Unlike public liability insurance, which is designed to respond to third-party claims, contract works insurance focuses on protecting the project itself before it reaches practical completion.
Exactly what is insured, when cover begins and when it ends will depend on the individual policy and the contractual arrangements applying to the project.
Works in progress remain vulnerable throughout construction
Landscaping projects are rarely completed in a single stage. Instead, they evolve progressively as different parts of the project are constructed.
Excavation is completed before drainage is installed. Irrigation systems may be placed beneath future garden beds. Retaining walls are often built before paving, planting and finishing works begin.
Each completed stage remains exposed while the remainder of the project continues.
Imagine a commercial landscape project where newly installed paving is damaged by machinery being operated by another contractor before practical completion. Alternatively, completed irrigation infrastructure may require replacement after accidental excavation elsewhere on the site.
Without appropriate insurance, these types of incidents may create substantial financial consequences before the client has even taken possession of the completed works.
Materials can represent a significant investment before installation
Many landscaping projects require materials to be delivered well before they are needed.
Pavers, natural stone, retaining wall systems, irrigation components, timber, lighting equipment, turf and plants may all remain stored on site awaiting installation.
These materials often represent a considerable financial investment, particularly on larger residential or commercial developments.
Depending on the policy wording, contract works insurance may provide protection for certain insured losses involving project materials before they become part of the completed works.
Storage arrangements, site security, policy conditions and the location of materials may all influence how cover applies. For this reason, contractors should understand how their policy treats materials stored at depots, in transit and on construction sites.
Practical completion does not always mean every risk has ended
The period leading up to practical completion can sometimes create confusion regarding responsibility for the project.
Although substantial work may have been completed, landscaping contractors often remain responsible for the works until practical completion has been achieved or the project has been formally handed over under the building contract.
This means completed landscaping features may still be exposed to accidental damage caused by weather events, site activity or other contractors continuing to work on the development.
Understanding exactly when responsibility transfers can help avoid misunderstandings if an incident occurs shortly before completion.
Weather can affect landscaping projects in different ways
Unlike many construction trades, landscaping businesses work almost entirely outdoors.
Heavy rainfall can erode newly prepared surfaces, flooding may damage materials stored on site and strong winds can affect fencing, plants, trees and partially completed structures before installation is complete.
Extreme weather may also delay project completion, increasing the amount of time works remain exposed before handover.
While insurance may respond to certain insured events, project planning, temporary protection measures and secure storage of materials remain important parts of managing weather-related risk.
Other contractors can influence project risk
Large landscaping projects often involve multiple trades working within the same construction area.
Electricians, plumbers, concreters, builders and civil contractors may all be undertaking work simultaneously.
Even where your own work has been completed to a high standard, accidental damage caused by another contractor can still affect completed landscaping works before practical completion.
Understanding contractual responsibilities, documenting completed stages and maintaining clear communication with the principal contractor can assist in resolving issues should damage occur during construction.
Contract works insurance forms part of a broader insurance programme
Although contract works insurance plays an important role during construction, it is only one part of a landscaping contractor’s overall insurance strategy.
Public liability insurance helps address claims involving third-party injury or property damage. Plant and machinery insurance may protect valuable equipment used on site. Commercial motor insurance supports business vehicles, while tools and equipment insurance focuses on portable business assets.
Looking at these policies together provides a more complete approach to managing project risks from the day work begins until the project is successfully completed.
For a broader understanding of how these different covers work together, see our guide to Landscaping Business Insurance in Melbourne: Managing Risk with the Right Cover.
Frequently asked questions
Does contract works insurance replace public liability insurance?
No. Contract works insurance and public liability insurance are designed for different purposes. Contract works insurance generally focuses on protecting the project itself before completion, while public liability insurance is intended to respond to third-party personal injury or property damage where your business is legally liable.
Are materials stored on site covered?
Depending on the policy wording, contract works insurance may provide cover for certain project materials awaiting installation. The location of the materials, security arrangements and policy conditions may all influence how cover applies.
Does contract works insurance cover completed landscaping work?
It may cover completed sections of work before practical completion or handover, subject to the policy wording. Once responsibility for the project transfers, different insurance arrangements may apply.
Does it cover weather damage?
Certain weather-related events may be covered where they fall within the scope of the policy. Whether cover applies depends on the circumstances, the cause of the damage and the terms of the insurance.
Protecting projects before they reach completion
The greatest investment in a landscaping project often exists long before the client takes possession of the finished work. Materials, labour and completed stages can all be exposed to unexpected events during construction, making the period before handover an important time to consider project insurance.
At Atlantic Insurance, we help landscaping contractors across Melbourne and Victoria understand how contract works insurance fits within a broader insurance programme. If you’re reviewing your current cover or preparing for larger landscaping projects, we can help you assess your insurance options and arrange cover that reflects the way your business operates.